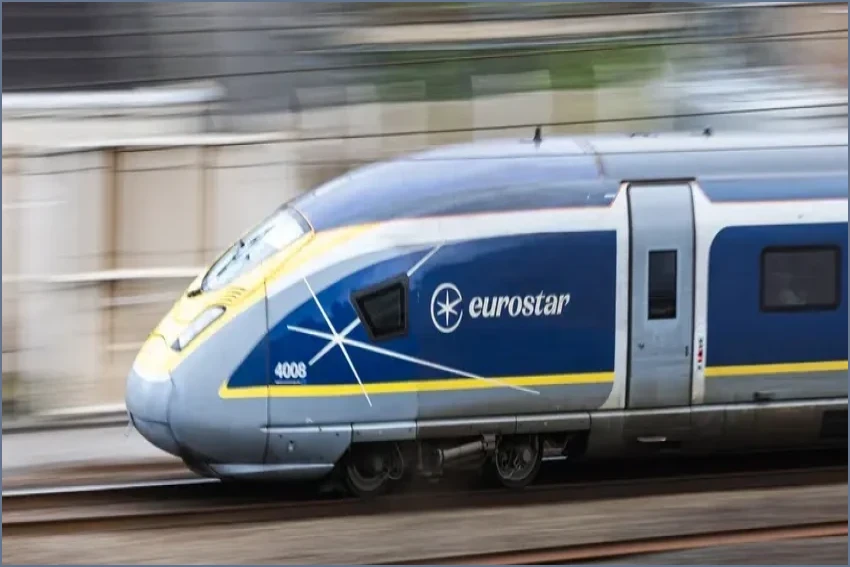
Since 1994, Eurostar has maintained a monopoly on high-speed rail services between London and Paris, a route known for its popularity but often high ticket costs. As new companies prepare to enter the market, travelers are questioning whether increased competition will finally lead to more affordable fares.
While several firms have announced intentions to compete, only the UK-based train company Virgin has successfully secured regulatory approval to access HS1, the high-speed line linking London to the Channel Tunnel.
Virgin’s current roadmap includes launching international services from London to Paris, Brussels, and Amsterdam by 2030, with plans for up to 20 daily return services. The company has also gained access to Temple Mills, Eurostar’s international maintenance depot in east London, a crucial piece of infrastructure for its operational success.
Marcus Mayers, a rail researcher who has written about Virgin's plans for The Conversation, noted that one of the biggest challenges for potential competitors is not simply getting permission to run trains, but being able to stable and service them. He believes Virgin is now in a strong position after securing this infrastructure access.
Mayers suggests that Virgin will likely differentiate itself from Eurostar through unique seating arrangements, family-friendly spaces, and customized passenger services rather than simply replicating the existing model. He noted that Virgin will want to establish a distinct identity, which would force Eurostar to respond.
Potential future expansions could include routes to Lille and other French cities, as noted by rail expert Mark Smith, who also highlighted that companies like Trenitalia could start operating trains between London and Paris by 2029.
Additionally, train company Gemini could explore more stops in France and expand to Germany from London, such as to Cologne.
Despite these plans, significant obstacles remain, most notably the stations themselves and the complexities of post-Brexit border controls. The London-Paris route crosses an external EU border, and since the end of the Brexit transition period, this has resulted in increased passport checks. These requirements are set to increase further with the full introduction of the EU's biometric passport checks, known as EES.
The extra requirements of passport stamping have significantly increased check-in time, leading Eurostar to advise passengers to arrive an hour or more before their train leaves. Travelers may have already noticed the overcrowded waiting area at St Pancras and the long queues at Paris’ Gare du Nord.
St Pancras is already struggling with the growing number of international passengers, with Eurostar trains carrying up to almost 900 people. Plans are under way to redesign the terminal, including changes intended to increase security-processing capacity and reduce waiting times, although they will not be completed for years.
Mayers, who worked at Eurostar in the 1990s, explained that the biggest constraint on adding more Channel Tunnel services is not the trains themselves, but the stations.
He noted that while trains can move in and out quickly, the current system of passport and security checks was not designed for the volume of international rail travel now being handled. He believes that Virgin's arrival could put pressure on the whole system to improve.
Regarding the prospect of cheaper tickets, experts remain cautious. The economics of international rail are very different from those of domestic French high-speed trains. Channel Tunnel operator GetLink charges companies for using the tunnel, using the fees to cover the costs of maintenance and security in the 50km undersea tunnel.
Independent railway commentator Jon Worth pointed out that the cost to operators of the tunnel fee works out at around €17 per passenger, in addition to all the usual expenses for train operators such as the cost of the train itself, maintenance, energy, and staff wages.
Consequently, he expects competition to drive up the number of trains and reduce prices a bit, but he cautioned that it probably will not result in a “Ryanair train.”
Mayers also cautioned against assuming that competition automatically means dramatically cheaper tickets. He noted that Virgin could put pressure on Eurostar even if its fares are not always lower, by offering a different product and giving passengers another reason to choose one operator over the other.
The market could therefore become bigger rather than simply being divided between Eurostar and Virgin. Ultimately, Mayers believes competition will sharpen both companies and could lead to more destinations, more creative train designs, and different types of passenger experience.